A Lender’s Take On AI
According to research, 74 percent of companies using AI say it has given them a competitive edge. This figure rises to 79 percent among companies that are leaders in AI deployment. To decipher this technology’s impact on mortgage lending, we thought it best to ask a top lender for his take. Our editors sat down with Franco Terango, CEO at Certainty Home Lending, to discuss AI and other future industry trends. Here’s what he said:
QUESTION: How is AI impacting Certainty Home Lending and how do you think AI is affecting the mortgage industry as a whole?
FRANCO TERANGO: At Certainty, the most meaningful impact of AI has been giving our loan officers more time to do the most important things, like building real relationships with borrowers and referral partners. A loan officer who can be genuinely present with a client rather than managing a queue of conditions and status updates tends to deliver a better experience and build a more durable book of business. For the industry broadly, I think the longer-term impact will show up in underwriting, where AI may help identify creditworthy borrowers whose financial profiles don’t fit conventional models particularly well. The technology is promising, but its value depends entirely on how lenders choose to deploy it.
QUESTION: What will the role of the LO really be after the dust settles from the AI transformation?
FRANCO TERANGO: The LO’s job was never really about shuffling documents. It has always been, at its core, about understanding a borrower’s situation well enough to find the right solution and explain it clearly. AI accelerating the mechanical side of the process just makes that distinction more visible. What remains is the ability to recognize that a consultant earning good money on a 1099 is not a risk problem or that a small business owner in year three of growth needs someone who can read their financials rather than just average them. Recognizing and properly handling that kind of nuance requires knowledge and judgment, and while maybe AI somehow will be able to do that down the road, it certainly can’t now.
QUESTION: With a growing share of well-qualified borrowers earning income outside the traditional W-2 framework, how is Certainty positioned to serve them?
FRANCO TERANGO: This is absolutely one of the most significant shifts we’re seeing in the borrower pool, and it’s been a deliberate focus for us. Certainty has built out a full alternative financing product suite, including bank statement programs, P&L loans, and asset depletion options, and we underwrite them in-house, which gives us real control over turnaround times and decision-making. Too many of these borrowers have had a frustrating experience elsewhere, and a slow or opaque process tends to confirm their worst assumptions about whether the mortgage industry can actually serve them. Having an experienced underwriting team that understands how to read a self-employed borrower’s financial picture, rather than just running it through a system designed for W-2 income, is where we think we can make a real difference for a segment of borrowers that is only going to grow.
QUESTION: What’s the next big transformation for our industry?
FRANCO TERANGO: I think it’s a long-overdue reckoning about who we’re actually building this industry to serve. The median first-time buyer is now 40 years old, often self-employed or independently contracted, and increasingly skeptical that the mortgage process was designed with someone like them in mind. Adapting to that reality, with the right products, trained loan officers, and underwriting infrastructure that reflects how people actually earn money today. Successful lenders have already moved well beyond waiting for the old normal to return. The tools and products already exist. The transformation is in whether lenders commit to deploying them seriously.
INSIDER PROFILE
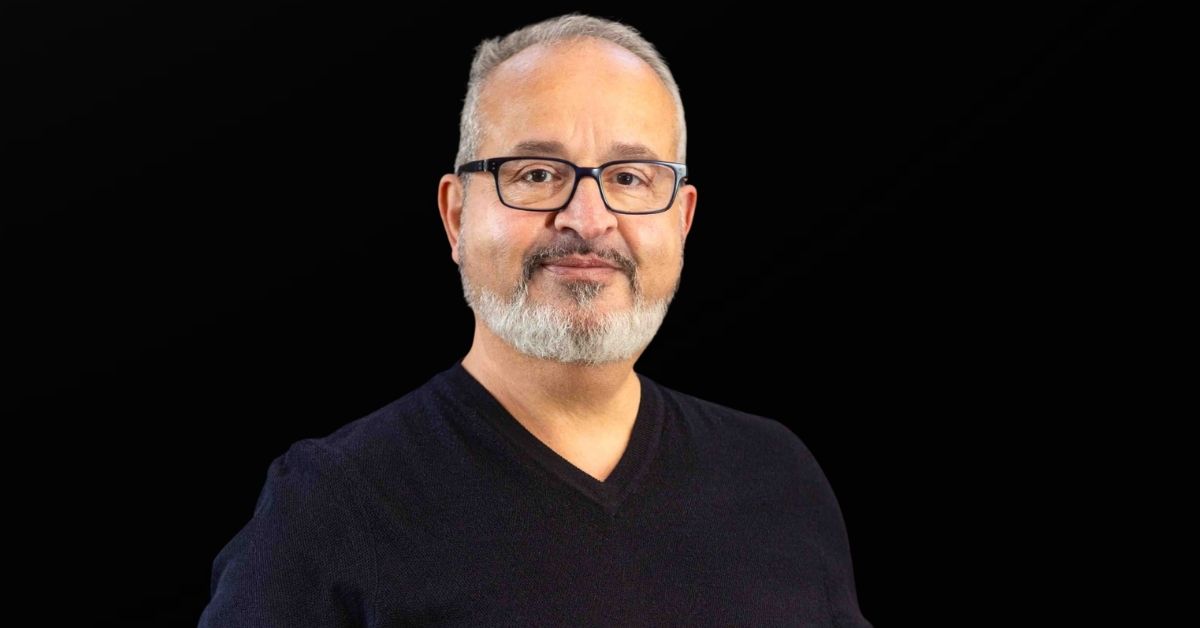
Franco Terango is CEO at Certainty Home Lending. Franco has been a leader in the financial services industry for over 35 years. During that span, he has demonstrated tremendous versatility, holding leadership positions traversing lines of business including consumer banking, investments, small business banking, and mortgage banking (25 years). Franco has long been driven to help others fulfill the dream of home ownership. He has done this by surrounding himself with highly skilled, incredibly professional mortgage sales originators who deliver exceptional expertise and service.
Franco has dedicated three decades to building highly successful teams across the country. His reputation is built on a foundation of integrity and performance. He firmly believes that the key to success in mortgage lending lies in creating a talented organization of elite mortgage professionals who can offer and deliver the best solutions to meet their clients’ diverse and unique needs.
The Place for Lending Visionaries and Thought Leaders. We take you beyond the latest news and trends to help you grow your lending business.